AI prompts for big money decisions you don't want to get wrong
Published
Short answerGive the AI your real numbers and ask it to lay out the comparison in a table with the costs people usually forget, such as maintenance and the cost of your time. Then check anything important with an official source or a qualified adviser before you commit.
Big money decisions rarely fail because of one bad number. They fail because of the costs nobody wrote down: the maintenance on a house, the interest on a "no-fee" deal, the resale value of a gadget nobody uses after month two. AI is good at this kind of work because it doesn't get bored laying out a full comparison table, and it won't let you skip the column you'd rather not look at.
It is not a financial adviser, and it can't know your local tax rules, lending terms or market conditions. Use it to organise your thinking and compare options side by side, then check anything that involves real money with an official source or a professional before you act.
1. Rent or buy: see the real comparison, not just the monthly number
Comparing a monthly rent to a monthly mortgage payment is the most common money mistake people make, because it leaves out deposits, maintenance, taxes and what your money would have earned elsewhere. The rent vs buy prompt asks for all of it:
Help me compare renting and buying a home in [CITY].

Price to buy: [PRICE]
Down payment: [AMOUNT]
Loan rate and term: [RATE AND YEARS]
Monthly rent for similar: [RENT]
How long I will stay: [YEARS]

Build a simple year-by-year comparison, list hidden costs on both sides, the assumptions that matter most and what I should check with a financial adviser. Not financial advice.
Pay close attention to "how long I will stay". Buying usually only wins over a long enough horizon, once you account for the costs of buying and selling. If you're not sure how long you'll stay, ask for the comparison at two different lengths of time side by side.
Include maintenance, taxes and the opportunity cost of your deposit for a fair comparison. These are the numbers people leave out, and they're usually the ones that change the answer.
2. Test whether you actually need the big purchase
Before you buy something expensive, whether that's a laptop, a sofa or a holiday, the big purchase prompt is a useful pause button:
I am thinking of buying [ITEM] for about [PRICE].

Why I want it: [REASONS]
My budget for it: [BUDGET]
Alternatives I have seen: [ALTERNATIVES]

Ask me five questions to test whether I really need it, calculate the cost per use over [YEARS] years, compare it with the alternatives including doing nothing, and give me a clear recommendation with the strongest counter-argument.
Cost per use is the most useful number this prompt produces. A £400 jacket worn twice a week for five years costs a few pence a wear. The same price spent on something used twice a year is a very different decision, even though the sticker price is identical.
3. Buying a used car without regretting it later
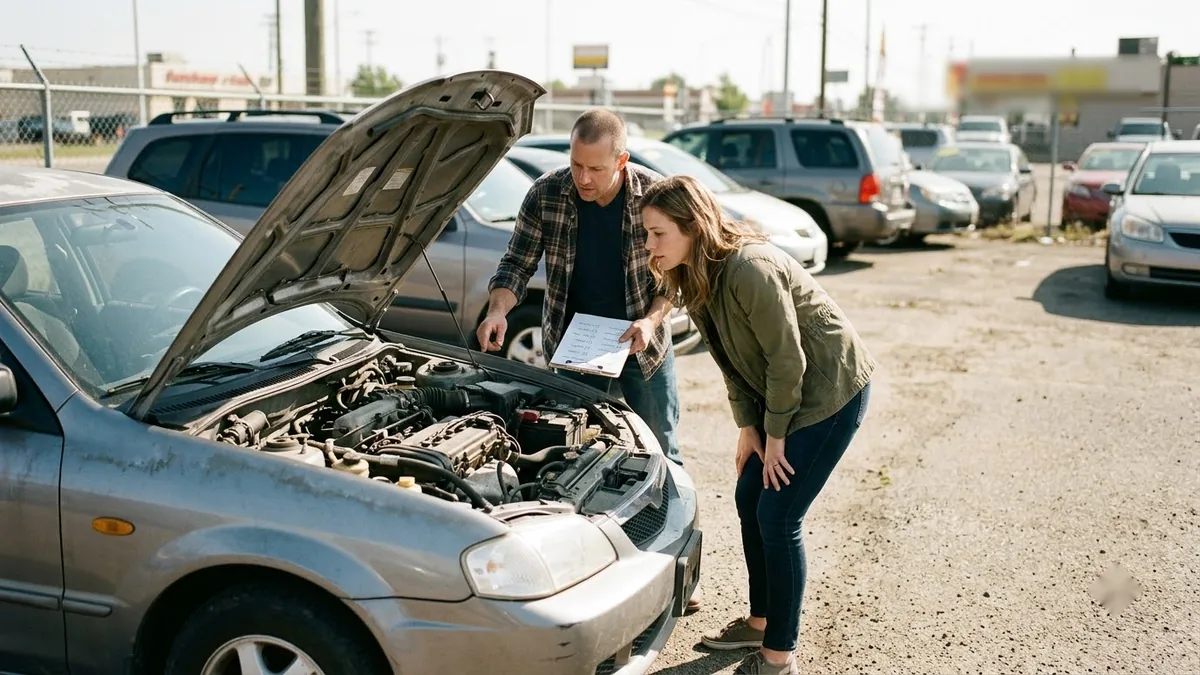
A used car is one of the easiest big purchases to get badly wrong, because the seller knows far more about the car's history than you do. The used car checklist prompt closes some of that gap:
Give me a checklist for buying a used [CAR TYPE] under [BUDGET].

Include paperwork to verify, questions to ask the seller, what to inspect outside, inside and under the bonnet, how to test drive, red flags, how to negotiate and what to do before paying.
The checklist can tell you what to look for; it can't actually look at the car. Always get an independent mechanic to inspect it before you pay, whatever the seller says about its condition. That single inspection is cheap compared with the repair bill it can save you from.
4. Build an emergency fund before you need one
An emergency fund isn't a big single purchase, but it's one of the biggest money decisions most people never properly plan, instead just hoping some savings happen on their own. The emergency fund prompt turns it into a concrete, time-bound plan:
Help me build an emergency fund.

Monthly income after tax: [AMOUNT]
Fixed monthly costs: [AMOUNT]
Current savings: [AMOUNT]
Debts and minimum payments: [DETAILS]

Work out a target for [3 / 6] months of essential expenses, propose a realistic monthly savings amount and timeline, list three places to trim spending, and suggest where to keep the money. This is for planning only, not financial advice.
Automate the transfer on payday rather than relying on moving money manually at the end of the month, once you've seen what's realistic. Willpower is the least reliable part of any savings plan; a standing order is not.
5. When you're stuck between two options
Some decisions aren't about a single number at all, they're about weighing things that don't compare easily, like a cheaper flat further from work against a pricier one closer in. For that, the decision helper prompt is built to slow you down before it gives an answer:
Help me decide between [OPTION A] and [OPTION B].

My situation: [CONTEXT, e.g. age, money, family, career goals]. What matters most to me: [PRIORITIES].

1. Ask me up to 3 clarifying questions first.
2. Then compare the options in a table: pros, cons, risks, cost, and long-term impact.
3. Tell me what would change your recommendation.
4. Give a clear final recommendation — don't just say "it depends".
Answer the clarifying questions as honestly as you can, even the uncomfortable ones. They shape the table that follows far more than any extra detail you add to the original question.
Common problems
The AI's numbers don't match your local rules. Tax treatment, stamp duty, loan fees and similar rules vary by country and change over time. Treat the structure of the comparison as the useful part, and get the actual figures confirmed locally.
You keep getting "it depends" as an answer. Ask again and say explicitly that you want a clear recommendation plus the strongest argument against it, not a list of considerations with no conclusion.
You want to check the numbers yourself. Ask for the comparison as a table you can copy into a spreadsheet, so you can swap in your own figures and watch the recommendation change.
Where to go from here
For the everyday version of this, building a monthly budget rather than a one-off decision, see AI prompts for budgeting and saving money. Moving house as part of the decision? AI prompts for renting and moving house covers the practical side. These prompts, and more like them, live in the productivity prompts collection, and the prompt builder can adapt any of them to your own numbers.
Quick checklist
- Use your real numbers, including the costs you'd rather forget about.
- Ask for hidden costs on both sides of a comparison, not just the headline figure.
- Work out cost per use before a big one-off purchase.
- Get an independent inspection before paying for a used car, whatever the checklist says.
- Automate savings rather than relying on moving money manually each month.
- Check anything that involves real money with an official source or adviser.

Comments
No comments yet. Be the first to share what worked for you.